Does the Federal Reserve set mortgage rates? No. The Fed sets a short-term rate, the Federal Funds Rate. Mortgage rates tend to follow the 10-year Treasury yield, which moves with inflation, the economy, and investor expectations. The Fed influences rates, but it doesn't control them.
You've probably seen the headlines that the Fed is raising rates again. If you're planning to buy or sell in San Diego County, you may be wondering what that means for you.
Here's the short answer: the next few months could be a little bumpy. But the Fed is playing the long game, and with the right plan, you can still make a move that works.
Why the Fed Is Raising Rates
It comes down to inflation. When prices rise quickly, buyers have less spending power and homes cost more to build.
To slow inflation, the Fed raises its key short-term rate, the Federal Funds Rate. That's where a lot of people get confused.
Myth: The Fed controls mortgage rates.
Reality: The Fed is one influence on mortgage rates, not the one setting them.
As NerdWallet explains:
“The Federal Reserve influences mortgage rates, but doesn't set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve's monetary policy is a factor, too . . .”
NerdWallet explains it well: inflation, job growth, and the overall direction of the economy all shape mortgage rates, and the Fed's policy is one more factor in that mix.
What Actually Moves Mortgage Rates
Mortgage rates tend to follow the 10-year Treasury yield, the return investors earn for lending the government money for 10 years. That yield rises and falls with what investors expect from inflation and the economy.
Right now, one of the biggest influences on that yield is the conflict in Iran. It's pushed oil prices higher, which has investors watching inflation closely. That's why news about the conflict can move mortgage rates. A resolution could ease some of that pressure, but the timing is hard to predict.
The Fed moves that yield too. When it raises rates to fight inflation, the 10-year yield can rise, and mortgage rates usually follow. Once inflation cools, the yield has room to come back down, and mortgage rates can follow it. That gives buyers some of their purchasing power back.
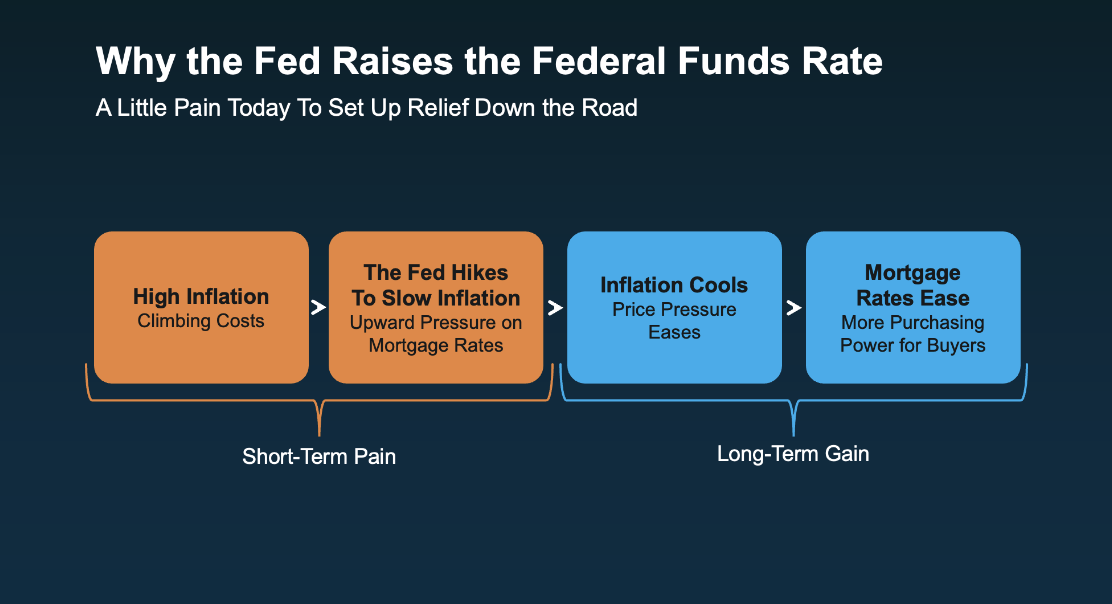
Think of it as some short-term pain to set up relief later.
Another Hike Is Likely This Year
According to CME FedWatch, there's more than an 80% chance the Fed raises rates at least once more before the end of 2026. That would likely keep upward pressure on mortgage rates in the short term.
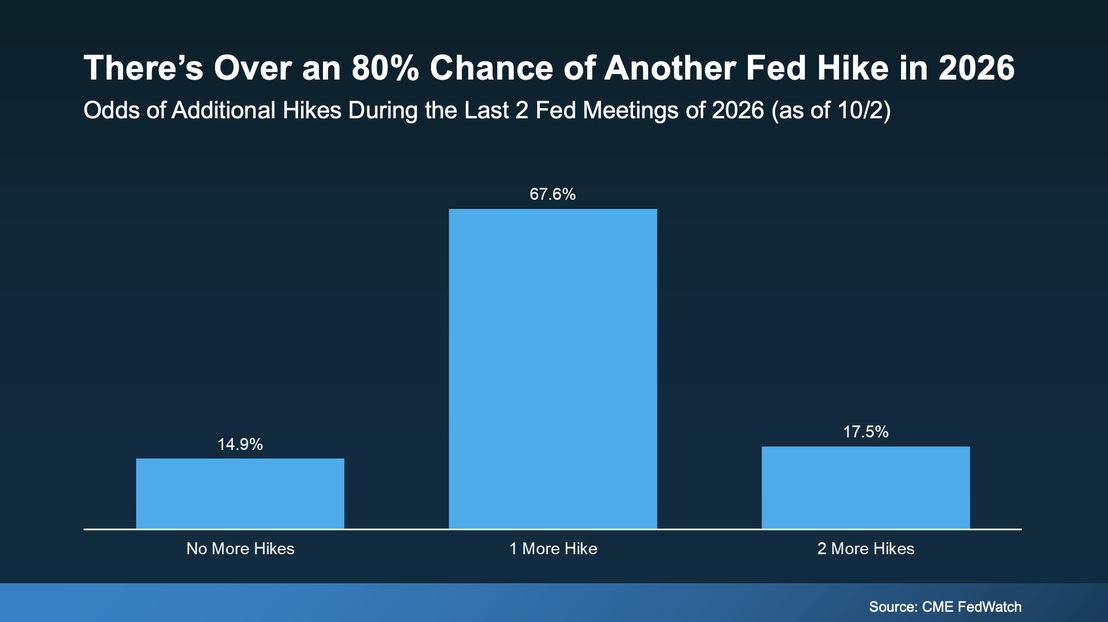
So should you wait it out? First American Senior Economist Sam Williamson notes that firmer Fed action could eventually steady the bond market and open the door to lower mortgage rates, but only once investors are convinced inflation is under control.
There are early signs of progress. Inflation cooled faster than expected in August:
PCE inflation dropped to 3.4%, down from 3.7% in July.
Core PCE, the Fed's preferred measure that excludes food and energy, fell to 3%, down from 3.3%.
That's part of why the odds of a hike at the Fed's October meeting have come down. But inflation is still above the Fed's 2% target, where it's been for about five years. Lower rates could take a while.
The best approach is a plan that works at today's rates.
How to Make Your Move Work Right Now
If You're Buying
Get pre-approved. Know your real budget before you start touring.
Ask your lender about your options. There may be ways to get a better rate than you expect.
Lock your rate once you're under contract. That protects your payment if rates jump before closing.
If You're Selling
Decide what matters most. A quick sale and top dollar can call for different strategies.
Price for today's buyers. Higher rates mean smaller budgets.
Consider a rate buydown or other concession. It can do more for a buyer's monthly payment than a price cut.
For buyers and sellers alike, it still comes back to location, condition, and price. Rates change. Those three fundamentals are what make a home the right fit and help it sell.
Frequently Asked Questions
Will mortgage rates go down if the Fed raises rates?
Not right away. Fed hikes can keep upward pressure on mortgage rates in the short term. Over time, if inflation comes down, mortgage rates have room to ease.
Should I wait for lower rates to buy in San Diego?
Lower rates could take a while, and more hikes are likely this year. A plan built around today's rates, with a pre-approval and a rate lock, lets you move forward with confidence.
What can sellers do when rates are high?
Price for what buyers can afford today, and consider concessions like a rate buydown, which can lower a buyer's monthly payment more than a price reduction.
Let's Build Your Plan
The Fed doesn't set mortgage rates, but its decisions can keep them higher for a while. If you're thinking about buying or selling in San Diego County, let's map out a plan that works at today's rates. Call or text me. I'm happy to help.
Billie Bourgeois | REALTOR® Real Broker | San Diego County, CA DRE# 01703336