Can paying rent help me qualify for a mortgage? It can. New credit models can count on-time rent payments, but it isn't automatic. You need to make sure your rent is being reported to the credit bureaus.
If you rent, your biggest monthly payment is probably your rent. You can pay it on time for years, and it may never show up on your credit report.
That's frustrating, especially if you want to buy a home someday. The good news: that's starting to change.
The Problem: Not Enough Credit History
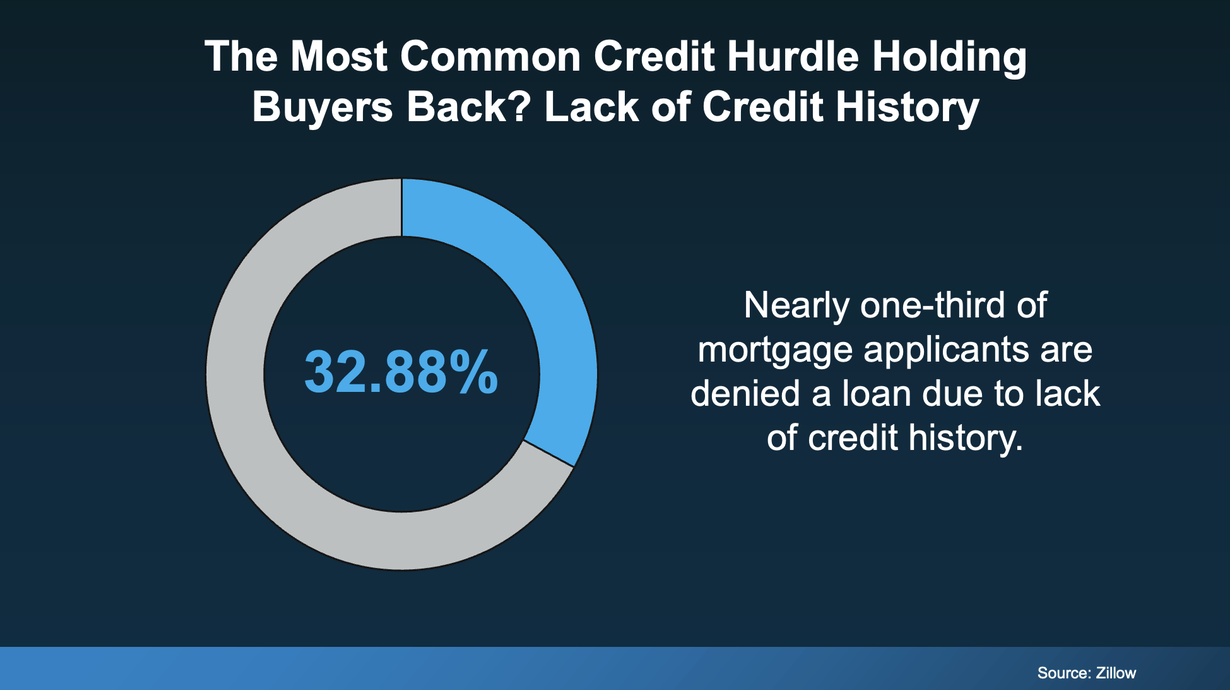
According to Zillow, nearly a third of mortgage applicants (32.88%) are denied because of insufficient credit history. Not missed payments. Not too much debt. Just not enough history for a lender to say yes.
It's the most common reason buyers get turned down.
“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
The Good News: Credit Is Getting Broader
Zillow Rentals' Michael Sherman says credit history is blocking too many potential buyers, and that rent reporting is a direct way to fix it.
"Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”
New credit models are starting to count on-time rent and some utility payments, so renters get credit for bills they already pay.
VantageScore has one of these models, and it's been approved by the Federal Housing Finance Agency (FHFA). A VantageScore study found nearly 4 million U.S. renters could become eligible for a mortgage if their on-time rent payments counted toward their credit history.
It's not a guarantee for every buyer. But it opens a door. You still have to walk through it.
Your Rent Won't Count Unless You Make Sure It Does
Here's how to get started, based on guidance from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:
Ask your landlord if your rent is reported. If it's not, opt in.
Use a rent reporting service if your landlord doesn't offer one. Check the fees and which credit bureaus they report to.
Check your credit reports for errors. Fixing mistakes is one of the fastest ways to strengthen your profile. The CFPB has step-by-step instructions.
Follow the basics. Pay bills on time, keep card balances low, and don't apply for a lot of new credit at once.
Keep old accounts open. Even paid-off accounts you rarely use help your history.
Build beyond rent. A secured credit card or becoming an authorized user on someone else's account can add to your history.
These steps take some time, but they add up. Not every lender uses the same scoring model, and more changes are coming, so the sooner you start, the better.
Talk to a Lender Early
Even if you're not sure when you'll be ready, a conversation with a loan officer is a smart first step. They can show you where you stand, build a plan, and give you a realistic timeline.
If you don't have a lender yet, I'm happy to connect you with one I trust.
Frequently Asked Questions
Does rent count toward my credit score?
Only if it's reported to the credit bureaus. Ask your landlord, or use a rent reporting service.
Why are mortgage applications denied?
According to Zillow, the most common reason is insufficient credit history, which accounts for nearly one-third of denials.
How can I build credit to buy a home?
Get your rent reported, check your reports for errors, pay bills on time, keep balances low, and keep old accounts open. A lender can help you build a plan.
See Where You Stand
The credit landscape is changing, but you have to take action to benefit. A quick conversation with a lender costs nothing and could show you're closer to owning a home in San Diego County than you think. Call or text me and I'll help you get started.
Billie Bourgeois | REALTOR® Real Broker | San Diego County, CA DRE# 01703336